A transaction is coming, and the numbers have to hold up to someone else's scrutiny.
A lender, a buyer or a seller is about to look at your financials harder than you ever have. What they find will set the price, the terms, or whether it happens at all.
What's usually going on
Diagnosis, not blame. These are the causes we find most often.
— Add-backs and owner expenses are tangled into the P&L.
— Working capital has never been measured, so a buyer's target will surprise you.
— The projection is optimistic and unsupported.
— On the buy side, the target's numbers are being taken at face value.
What we'd look at first
Written for the person who'll check whether we know what we're talking about.
01
A normalized P&L with every adjustment documented.
02
A working-capital baseline over the trailing twelve months.
03
Quality of the receivables and inventory a buyer will discount.
04
The debt schedule and what gets paid off at close.
05
On the buy side: whether the target's cash actually reconciles to its P&L.
What changes
What you get
A data room that answers questions before they're asked, a projection a lender or buyer can test, and a working-capital position you set rather than accept.
What improves
The numbers hold up to someone else's scrutiny.
What you can now decide
Whether the deal works, what to negotiate, and what the business is likely worth before anyone tells you.
Where to go from here
Tell us what's going on. We'll tell you what we see
One conversation with Chris, no deck. He'll tell you what he sees and what it would take to fix it, including if the answer is that you don't need a CFO yet.
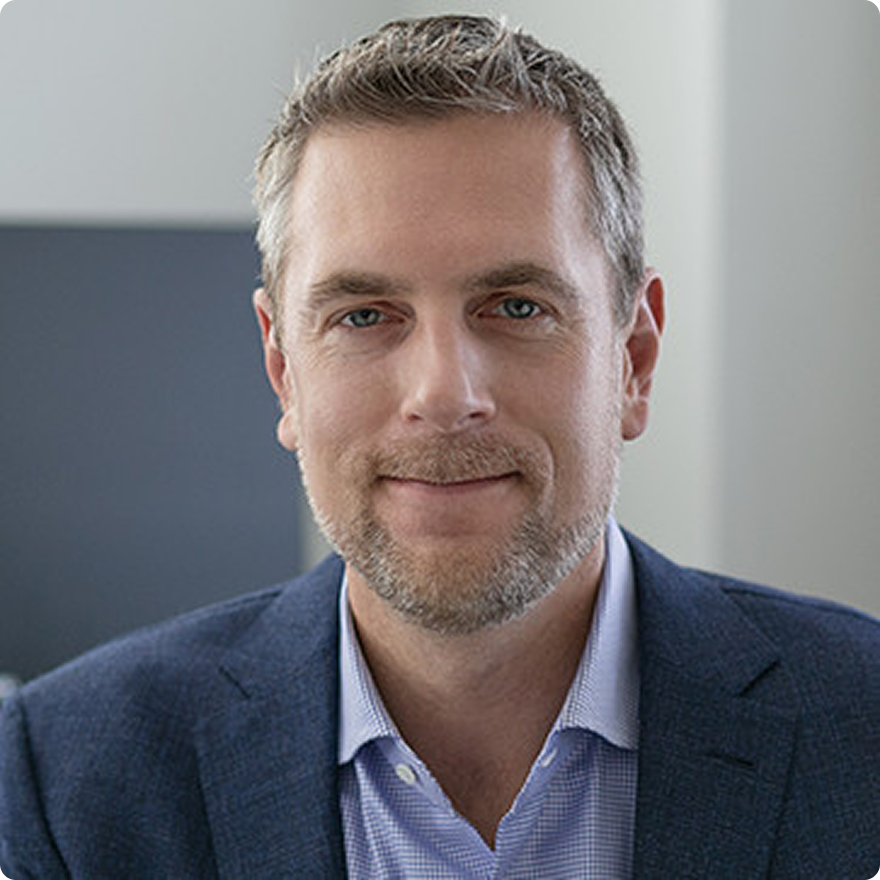
Chris Greco, Founder and President.
Your first call is with him, not a sales team.