The bank is asking questions your books can't answer cleanly.
Line renewal, a new equipment loan, an SBA request, or an annual review, and the lender wants financials that tie to the tax return, a projection with assumptions, and a covenant calculation. Your books can't produce it without a scramble.
What's usually going on
Diagnosis, not blame. These are the causes we find most often.
— Internal statements and the tax return were prepared by different people with different rules.
— The balance sheet hasn't been reconciled in a while and the lender's analyst noticed.
— Nobody has been tracking covenants between reviews.
— The last projection was built for the last loan and never updated.
What we'd look at first
Written for the person who'll check whether we know what we're talking about.
01
The bridge between the internal balance sheet and the return.
02
Every balance sheet account with an unreconciled balance.
03
The loan agreement's covenant definitions, calculated the way the bank calculates them.
04
Global cash flow, if the owner guarantees.
05
What the credit memo will need that you don't currently produce.
What changes
What you get
A lender package the analyst can underwrite without follow-up questions, a projection with written assumptions, and a covenant calendar.
What improves
The business becomes an easy borrower.
What you can now decide
Renew without a fire drill, borrow for the next truck or building on your timeline, and know before the bank does if a covenant is at risk.
Where to go from here
Tell us what's going on. We'll tell you what we see
One conversation with Chris, no deck. He'll tell you what he sees and what it would take to fix it, including if the answer is that you don't need a CFO yet.
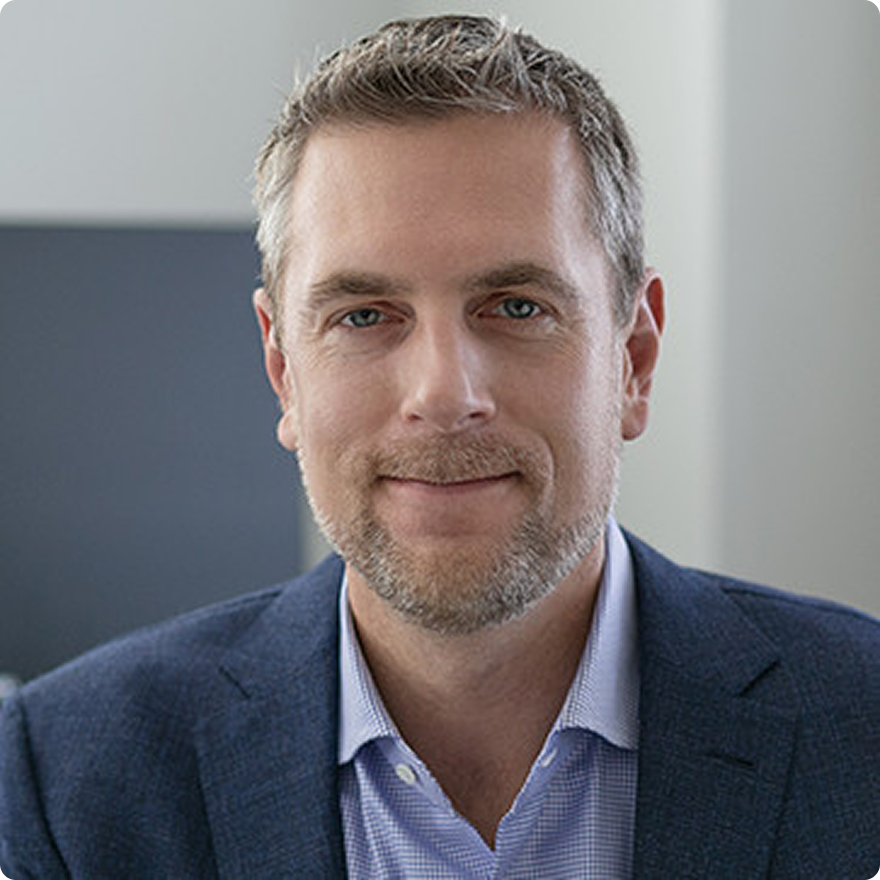
Chris Greco, Founder and President.
Your first call is with him, not a sales team.