Financials your banker can actually use.
Loan packages, projections and ongoing lender reporting from a team that has sat on the borrower's side of the table for more than twenty years.
When you need this
You're applying for a loan, a line, SBA financing, equipment or a building. Your line is up for renewal. The bank asked for financials you don't have. Your internal statements don't match your tax return and someone noticed. You have covenants and nobody is tracking them.
What we look at
— The bridge from internal statements to the return.
— Every unreconciled balance sheet account.
— Covenant definitions calculated the bank's way.
— Debt service coverage, global cash flow if you guarantee, and the borrowing base if you have one.
— What the credit memo will need.
What we build or change
Loan packages
— Historical financials in the lender's format.
— Projections with written assumptions and debt schedules.
— Personal financial statement support.
— A narrative that explains the request in the lender's terms.
— Cleanup so the books tie to the returns.
Ongoing
— Monthly or quarterly lender packages.
— Covenant compliance certificates and borrowing base certificates.
— Annual review packages, on a calendar so nothing is late.
— An early call to your banker when the forecast shows trouble ahead, with your consent.
What changes for you
What you get
A package the analyst can underwrite without follow-up.
What improves
The business becomes an easy borrower with a covenant calendar instead of an annual scare.
What you can now decide
Borrow on your timeline, renew without a fire drill, and know before the bank does if a ratio is drifting.
For the person checking our work
SBA 7(a) and 504, conventional term and lines, equipment and commercial real estate. DSCR, fixed-charge coverage, leverage, borrowing base, global cash flow. We speak the language because we've prepared the packages.
Why it's affordable. Loan packages are a fixed fee, quoted before we start, deliberately kept low because they're how many long-term client relationships begin. Some owners just get their loan. Either outcome is fine with us.
What it looks like
Sample lender package, index
Line renewal · conventional
1.
Request summary in the lender's terms
2.
Historical financial statements, three years, tied to the returns
3.
Interim statements, year to date, reconciled
4.
Projection with written assumptions and debt service
5.
Debt schedule, tied to lender statements
6.
Covenant compliance certificate, calculated the bank's way
7.
Receivables and payables aging; personal financial statement support
Sample. Assembled so the analyst can underwrite without a follow-up list.
Questions we get about this
What does a loan package include?
Historical financials in the lender's format, a projection with written assumptions, debt schedules, PFS support and a narrative the banker can lift into the credit memo.
How long does it take?
Typically ten business days once we have bank statements, prior returns, your current books and the lender's list.
Do you work with our banker directly?
Yes, and nothing goes to them without you seeing it first.
Related
Tell us what's going on. We'll tell you what we see
One conversation with Chris, no deck. He'll tell you what he sees and what it would take to fix it, including if the answer is that you don't need a CFO yet.
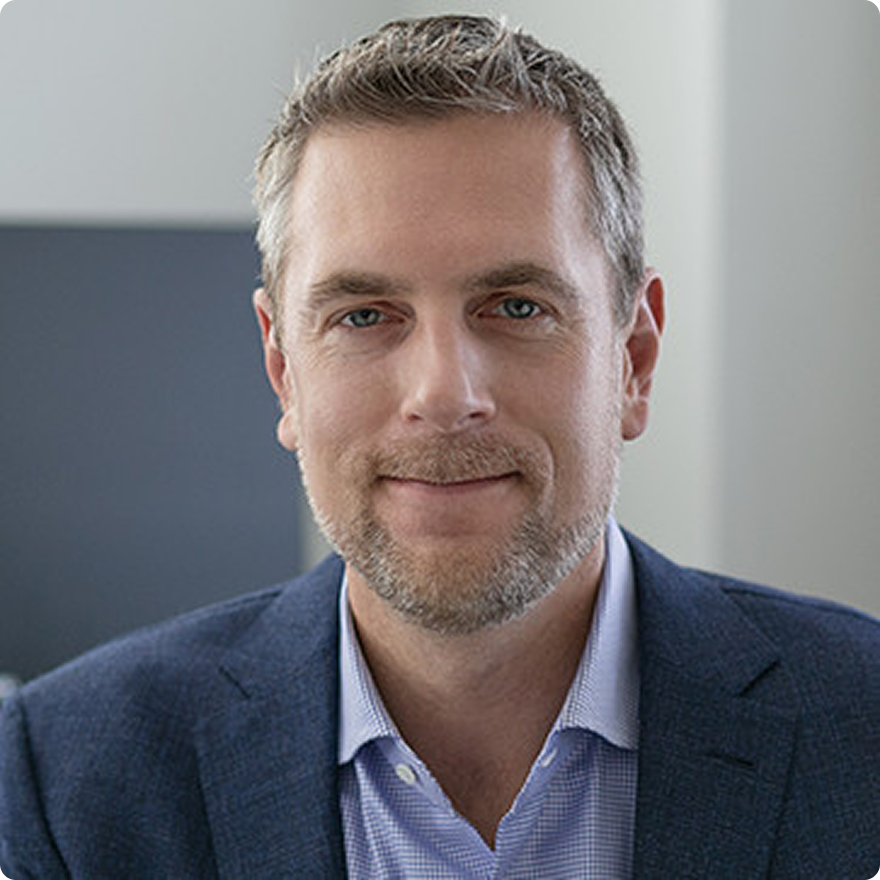
Chris Greco, Founder and President.
Your first call is with him, not a sales team.